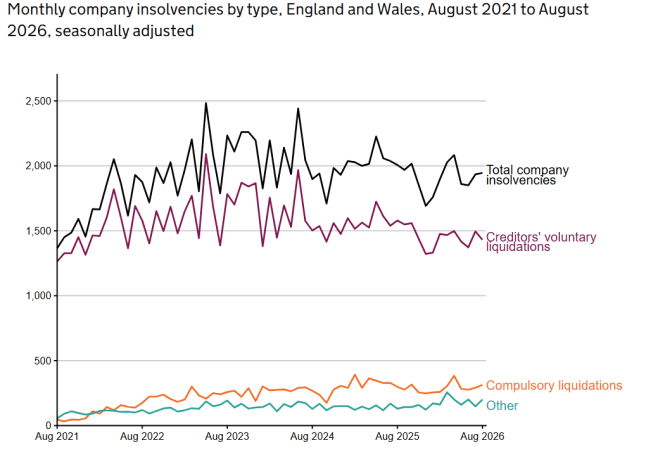
There were 1,946 company insolvencies in August 2026, 1% higher than in July 2026 but 3% lower than in August 2025. August 2026 saw lower numbers of CVLs but higher compulsory liquidations and administrations than July 2026.
CVLs
In August 2026, CVLs accounted for 74% of all company insolvencies. The number of CVLs was 4% lower than in July 2026, and 9% lower than in August 2025. The average monthly number of CVLs in the first eight months of 2026 was 7% lower than the average monthly number in 2025.
In 2025 CVL volumes slightly decreased by 2% from 2024 and by 10% from the record-high number registered in 2023. The past four years have seen the highest four numbers of CVLs since the time series began in 1960. Between 2017 and 2019, CVLs had been rising at approximately 10% per year, but during the COVID-19 pandemic, they fell to their lowest levels since 2007.
Compulsory liquidations
The number of compulsory liquidations in August 2026 was 8% higher than in July 2026 and 5% higher than in August 2025. The average monthly number of compulsory liquidations in the first eight months of 2026 was 5% lower than the 2025 monthly average.
In 2025, compulsory liquidations were at the highest levels since 2012, having increased by 15% compared to 2024 volumes. This continued an increase from record low levels seen in 2020 and 2021, while restrictions applied to the use of statutory demands and certain winding-up petitions (leading to compulsory liquidations).
Administrations
The number of administrations in August 2026 was 44% higher than in July 2026 and 60% higher than in August 2025. The average monthly number of administrations in the first eight months of 2026 was 36% higher than the 2025 monthly average. This was driven by higher numbers between March and August 2026, when more than 250 connected companies in the Real Estate sector entered administration.
What Is The Trend?
Last month there was a slight uptick in the number of insolvencies but this now seems to have been reversed.
This backs up some signs that insolvency volumes are easing compared with the very high levels seen in recent years. The average monthly number of CVLs during the first seven months of 2026 was 7% lower than the 2025 average, while compulsory liquidations were 6% lower.
More broadly, average monthly company insolvencies during 2026 have been 6% lower than the monthly average recorded over the preceding three years. This has mainly been driven by lower numbers of CVLs.
So, while insolvency levels remain high, the current picture looks more like a period of stabilisation than a renewed upward trend.
The wider business environment has not changed significantly. Many companies continue to face pressure from employment costs, energy prices, borrowing costs, weak demand and historic debt.
However, these pressures are not currently translating into a fresh surge in formal insolvencies.
Our experience earlier in 2026 was that HMRC had increased enforcement activity against companies with tax debts that had been allowed to build up over a long period. This included winding-up petitions and greater use of enforcement officers.
Such action can often become the immediate trigger for either a compulsory liquidation or for directors to place a company into creditors’ voluntary liquidation.
For now, the August figures suggest that insolvency levels are in fact falling.
What is very interesting is that there was a similar fall in August 2024. Keen readers will note that this was a couple of months prior to the first big labour budget under Rachel Reeves. We are seeing similar falls of insolvencies prior to the next big Budget under Any Burnham. Could it be that HMRC and other creditors are holding back a bit. It is more likely though that during periods of uncertainty big decisions are not taken that can have a knock on effect on the insolvency statistics.